What is blockchain technology? It is a shared digital record book. Several computers keep the same copy of the list. New entries are grouped into blocks, and each block links to the one before it. That link makes old records hard to change.
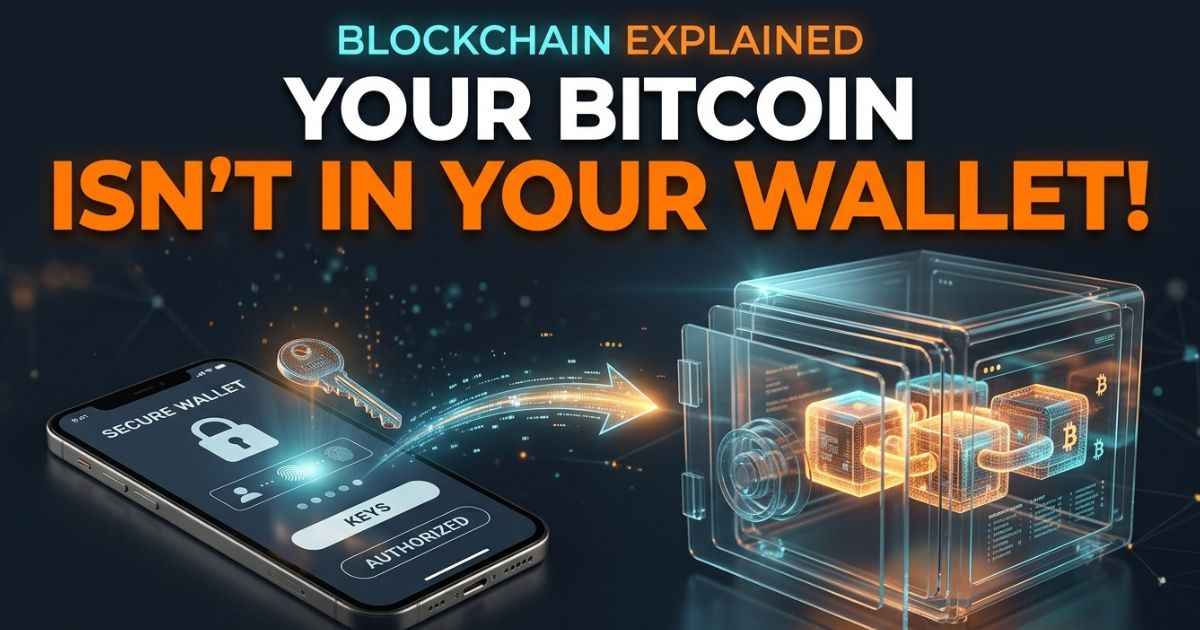
Here is a twist that surprises beginners: your crypto wallet does not hold any coins. The coins exist as records on the blockchain. This guide follows one Bitcoin payment from start to finish, so the pieces finally fit together.
What Is Blockchain Technology?
The U.S. National Institute of Standards and Technology (NIST) calls blockchain a shared digital ledger. It says the ledger is tamper-evident and tamper-resistant. A ledger is a record of transactions or other entries. It can also track who owns an asset.
Think of a notebook that a whole group shares. Everyone has the same copy. When someone wants to add a line, the group checks it first. Then everyone updates their copy.
Blockchain works in a similar way. Records are grouped into blocks. Each block is linked to the block before it by a cryptographic link, which is a math-based tie that is hard to fake. Together, the blocks form a chain.
Here are the key terms in plain words:
- Node: a computer that connects to a blockchain network. Full nodes store and check blockchain data, while other nodes may keep only part of it.
- Consensus: the rules a network uses to agree on new records.
- Block: a group of records saved together.
Is Blockchain the Same as a Distributed Ledger?
Not quite. A distributed ledger is a shared record kept in several places. Blockchain is one type of distributed ledger.
The European Commission explains that a distributed ledger can be built with other technologies too. So every blockchain is a distributed ledger, but not every distributed ledger is a blockchain.
How Does Blockchain Work?
Most blockchains follow a similar basic process. Someone proposes a transaction, network participants check it, and a valid block becomes part of the chain. The exact steps depend on the network.
Here is the path in seven steps:
- Someone starts a transaction. A transaction is a request to add a record, such as sending Bitcoin.
- The request goes to the network. Nodes receive it.
- Nodes check the request. They test it against the network’s rules.
- The network agrees. It uses its consensus method to decide the record is valid.
- The record goes into a block. It sits with other records that were approved.
- The block links to the chain. It points back to the block before it.
- Full nodes update their copies. Now they hold the same, longer chain.
What Is Inside a Blockchain Block?
A block holds a few simple parts. IBM explains that blocks carry transaction details, a timestamp, and a link to the block before.
| Part of a block | What it does |
|---|---|
| Transaction details | Show what was recorded |
| Timestamp | Shows when the block was added |
| Link to the previous block | Ties the block to the chain |
The link is made with a cryptographic hash. A hash is like a digital fingerprint made from data. If the data changes, the fingerprint changes too.
What Are Nodes and Consensus?
Nodes and consensus answer two different questions. Nodes answer “who keeps the records?” Consensus answers “how do they agree?”
| Nodes | Consensus | |
|---|---|---|
| What it is | Computers that connect to the network. Full nodes store and check blockchain data, while other nodes may keep only part of it | The rules for agreeing on new records |
| Main job | Check new entries and help keep the record | Decide which new records are valid |
| Simple picture | The group members holding the notebook | The group vote on each new line |
Consensus methods differ from one blockchain to another. NIST describes two common ones, proof of work and proof of stake. Bitcoin uses proof of work. Ethereum uses proof of stake, and its own documentation says it switched from proof of work in September 2022. Ethereum’s design also uses validators, which are the participants who help confirm new blocks.
This is why you should never say that all blockchains work the same way. Always check which network you are reading about.
What Happens When You Send Bitcoin?
Some beginners say they understand every word but still miss the process. This example puts the words in order.
First, a quick look at wallets. One Reddit explanation compares a Bitcoin address to a glass letterbox and a wallet to a keychain. The keychain holds your keys. The coins themselves are records on the blockchain.
Keys come in two kinds. A private key is a secret code used to sign transactions. The signature shows that the transaction meets the network’s authorization rules. Anyone who controls the key may be able to spend the linked funds.
A public key is used to check digital signatures. A public key can be shared. A Bitcoin address is a payment identifier created from a public key or other script information. It is commonly made from a public-key hash, so the two are not exactly the same thing. Both are different from the private key. IBM explains that blockchains use public key cryptography for this.
Now the payment:
- You press Send. In your wallet app, you enter the address and the amount.
- Your wallet signs the request. It uses your private key. The signature shows that the payment meets the network’s authorization rules.
- Your wallet broadcasts the request to the Bitcoin network. Nodes receive it.
- Nodes check it. Bitcoin nodes test it against the network’s rules.
- A miner may include it in a new block. Miners use proof of work to produce new blocks. Other nodes verify those blocks before accepting them.
- The block links to the chain. It points back to the block before it. Your payment gets its first confirmation when that block joins the accepted chain.
- The shared record changes. Full nodes update their copies. The blockchain now shows your payment.
This answers three common beginner questions:
- Where is the Bitcoin? It is recorded on the blockchain.
- Who checks the payment? The nodes on the network.
- What changes after you press Send? Your wallet broadcasts the transaction. Bitcoin nodes check it, and a miner may include it in a new block. The payment receives its first confirmation when that block joins the accepted chain.
Bitcoin uses blockchain technology to record transactions between addresses. The records are public, but the people behind those addresses are not automatically identified.
What if you delete a wallet app or switch computers? The blockchain record stays where it is. With a self-custody wallet, your private keys control your funds. With a custodial exchange account, the platform may hold those keys for you. Many self-custody wallets provide a recovery phrase, usually containing 12 or 24 words. It helps restore the keys if you lose access to your wallet. Read your own wallet’s instructions to learn how it works.
Why Are Blockchain Records Hard to Change?
Each block links to the one before it. So if someone changes an old block, the links no longer match. The change can be spotted.
Adding new blocks on top makes old records even harder to modify. In Bitcoin, confirmations build over time. Each additional accepted block makes changing an earlier transaction more difficult.
That is why NIST uses the words “tamper-evident” and “tamper-resistant.” It does not say “impossible to change.”
This small difference matters. Some websites say blockchain is “unchangeable” or “tamper-proof.” That is too strong. Cloudflare explains that blockchains are built to resist tampering, but it does not promise that every setup is free of risk. Treat blockchain records as hard to change, not magic.
What Are the Types of Blockchain Networks?
Blockchain networks differ in who can join and who is in charge. AWS and Cloudflare describe four common types: public, private, consortium, and hybrid. Other sources use different classifications.
| Type | Who can join | Who is in charge |
|---|---|---|
| Public | Participation is generally open, but permission rules can vary | No single owner |
| Private | Only people approved by one organization | That one organization |
| Consortium | Only approved members of a group | Several organizations share control |
| Hybrid | A mix of open and limited access | Depends on the network’s design |
A hybrid network combines public and permissioned components, with control depending on its design.
Do not mix this up with consensus. Network type tells you who can take part. Consensus tells you how the group agrees. A network can be public and still use proof of stake, as Ethereum does.
Is Bitcoin the Same as Blockchain?
No. Cloudflare and Coinbase both explain the difference. Bitcoin is a cryptocurrency. Blockchain is the technology that Bitcoin uses to keep its records.
| Blockchain | Bitcoin | |
|---|---|---|
| What it is | A way to keep a shared record | A cryptocurrency |
| Relationship | The technology | Uses the technology |
| Can it do other jobs? | Yes, such as keeping records | Mainly works as digital money |
Ethereum is another example. It is a blockchain that also runs smart contracts, which you will meet below.
What Is Blockchain Used For?
Blockchain is best known for cryptocurrency. But NIST points to other possible uses too. Here are four of them.
| Use | What gets recorded |
|---|---|
| Manufacturing supply chains | Product movements reported by suppliers, carriers, and other approved participants |
| Data registries | Entries in a shared list |
| Digital identity | Records or shares identity credentials that trusted issuers and verifiers can check |
| Records management | Documents and their history |
Blockchain can protect recorded information from later changes. It cannot independently confirm that every reported physical event actually happened.
The company Consensus describes blockchain-based electronic signatures as a business application. Its page explains how its jSign solution can record information about electronic signatures.
Be careful with long lists of uses. The European Commission explains how blockchain networks share information and validate new records. Check individual projects separately before describing their current status. A pilot or a proposal is not the same as a working service. When you read a claim, ask whether it is live today.
What Are Smart Contracts?
A smart contract is a program that lives on a blockchain. Ethereum’s documentation explains this well. Think of a simple “if this, then that” rule. If a payment reaches the contract, the program can transfer a digital item or trigger another on-chain action, which means an action done on the blockchain. Physical delivery needs an outside system to carry it out.
Smart contracts come with limits. On Ethereum, deploying a contract costs gas. Gas measures the computing work needed for an Ethereum transaction. The gas fee is the amount paid to process that transaction. Even a simple ETH transfer costs gas.
Smart contracts also cannot find real-world facts on their own. They need outside data tools, called oracles, to bring in facts such as a delivery date.
Blockchain vs a Traditional Database: What’s the Difference?
People often ask why anyone would use a blockchain instead of a normal database. It is a fair question. Both communities that talk about crypto and communities that talk about databases have asked it.
The European Commission gives a clear contrast. A traditional database has an owner who keeps it. A blockchain has network members who each keep a copy.
| Traditional database | Blockchain | |
|---|---|---|
| Who controls it | One owner | The network, based on its rules |
| Who updates it | The owner or people the owner allows | Participants, after the network agrees |
| Copies | Controlled by the owner, but it can also keep copies across several servers | Kept by several nodes |
| Agreement | The owner decides | Consensus decides |
| Fits best when | One party can run the records | Several parties must share a record without one central keeper |
So when might you not need a blockchain? If one group runs the records and everyone already trusts that group, a normal database may be enough. Some people on crypto forums say projects force blockchain into places where it does not fit. That is an opinion, not proof. Still, it is a smart question to ask before using the technology.
What Are the Benefits and Risks of Blockchain Technology?
Blockchain solves some problems well. It also has limits. This table pairs each upside with its catch.
| Topic | Upside | Catch |
|---|---|---|
| Records | Hard to change and easy to check for changes | Not literally impossible to change |
| Control | No single owner holds the only copy | Not every problem needs this setup |
| Smart contracts | Rules can run automatically | They cost gas on Ethereum and cannot see real-world facts alone |
| Security | Built to resist tampering | No setup is free of risk |
Blockchain is not a fix for every problem. Use it when several people need to share and trust one record.
Current Checks
Some blockchain facts change. Check these before you rely on them.
| Item | What to check | Source to use |
|---|---|---|
| Consensus method | Whether a network has changed how it agrees. Ethereum moved to proof of stake in September 2022. | The network’s official documentation |
| Transaction fees | Fees depend on the network and its conditions | The network’s official documentation |
| Speed | How fast a network handles transactions | The network’s official documentation |
| Energy use | Depends on the consensus method and the network | The network’s official documentation |
| Real-world uses | Whether a project is live, a pilot, or only a proposal | The project’s own announcements |
| Legal rules | Rules for crypto and blockchain businesses | Official U.S. government and regulator sources |
Frequently Asked Questions About Blockchain Technology
What is the main purpose of blockchain?
Its main purpose is to keep a shared record that several people can trust. No single owner has to hold the only copy. The network checks new entries and agrees before it adds them.
What is an example of blockchain?
Bitcoin is the best-known example. It uses blockchain technology to record transactions between addresses. The records are public, but the people behind those addresses are not automatically identified. Ethereum is another example, and it also runs smart contracts.
Is Bitcoin a blockchain?
No. Bitcoin is a cryptocurrency that uses blockchain technology. Blockchain is the system that stores the records. Bitcoin is one use of that system.
Can I withdraw my money from blockchain?
Blockchain is a technology, not a bank account. It does not hold your money in one place. Cryptocurrency is recorded on the blockchain. With a self-custody wallet, your private keys control your funds. With a custodial exchange account, the platform may hold those keys for you.
Can blockchain data be changed?
It is very hard, but do not call it impossible. NIST describes blockchains as tamper-evident and tamper-resistant. Changes to old blocks can be spotted, and new blocks make old records harder to modify.
Does every blockchain use mining?
No. Bitcoin uses proof of work. Ethereum uses proof of stake, and its documentation says it switched in September 2022. The method depends on the network.
Can a blockchain be hacked?
Blockchains are built to resist tampering. But Cloudflare notes that blockchain technology has risks and challenges. Security depends on the network and how it is set up, so it is wrong to promise that any blockchain is free of risk.
You May Find These Interesting:
BagelTechNews.com Tech News: What the Site Covers and How Reliable It Is
MyApps Login: How to Access the Microsoft My Apps Portal